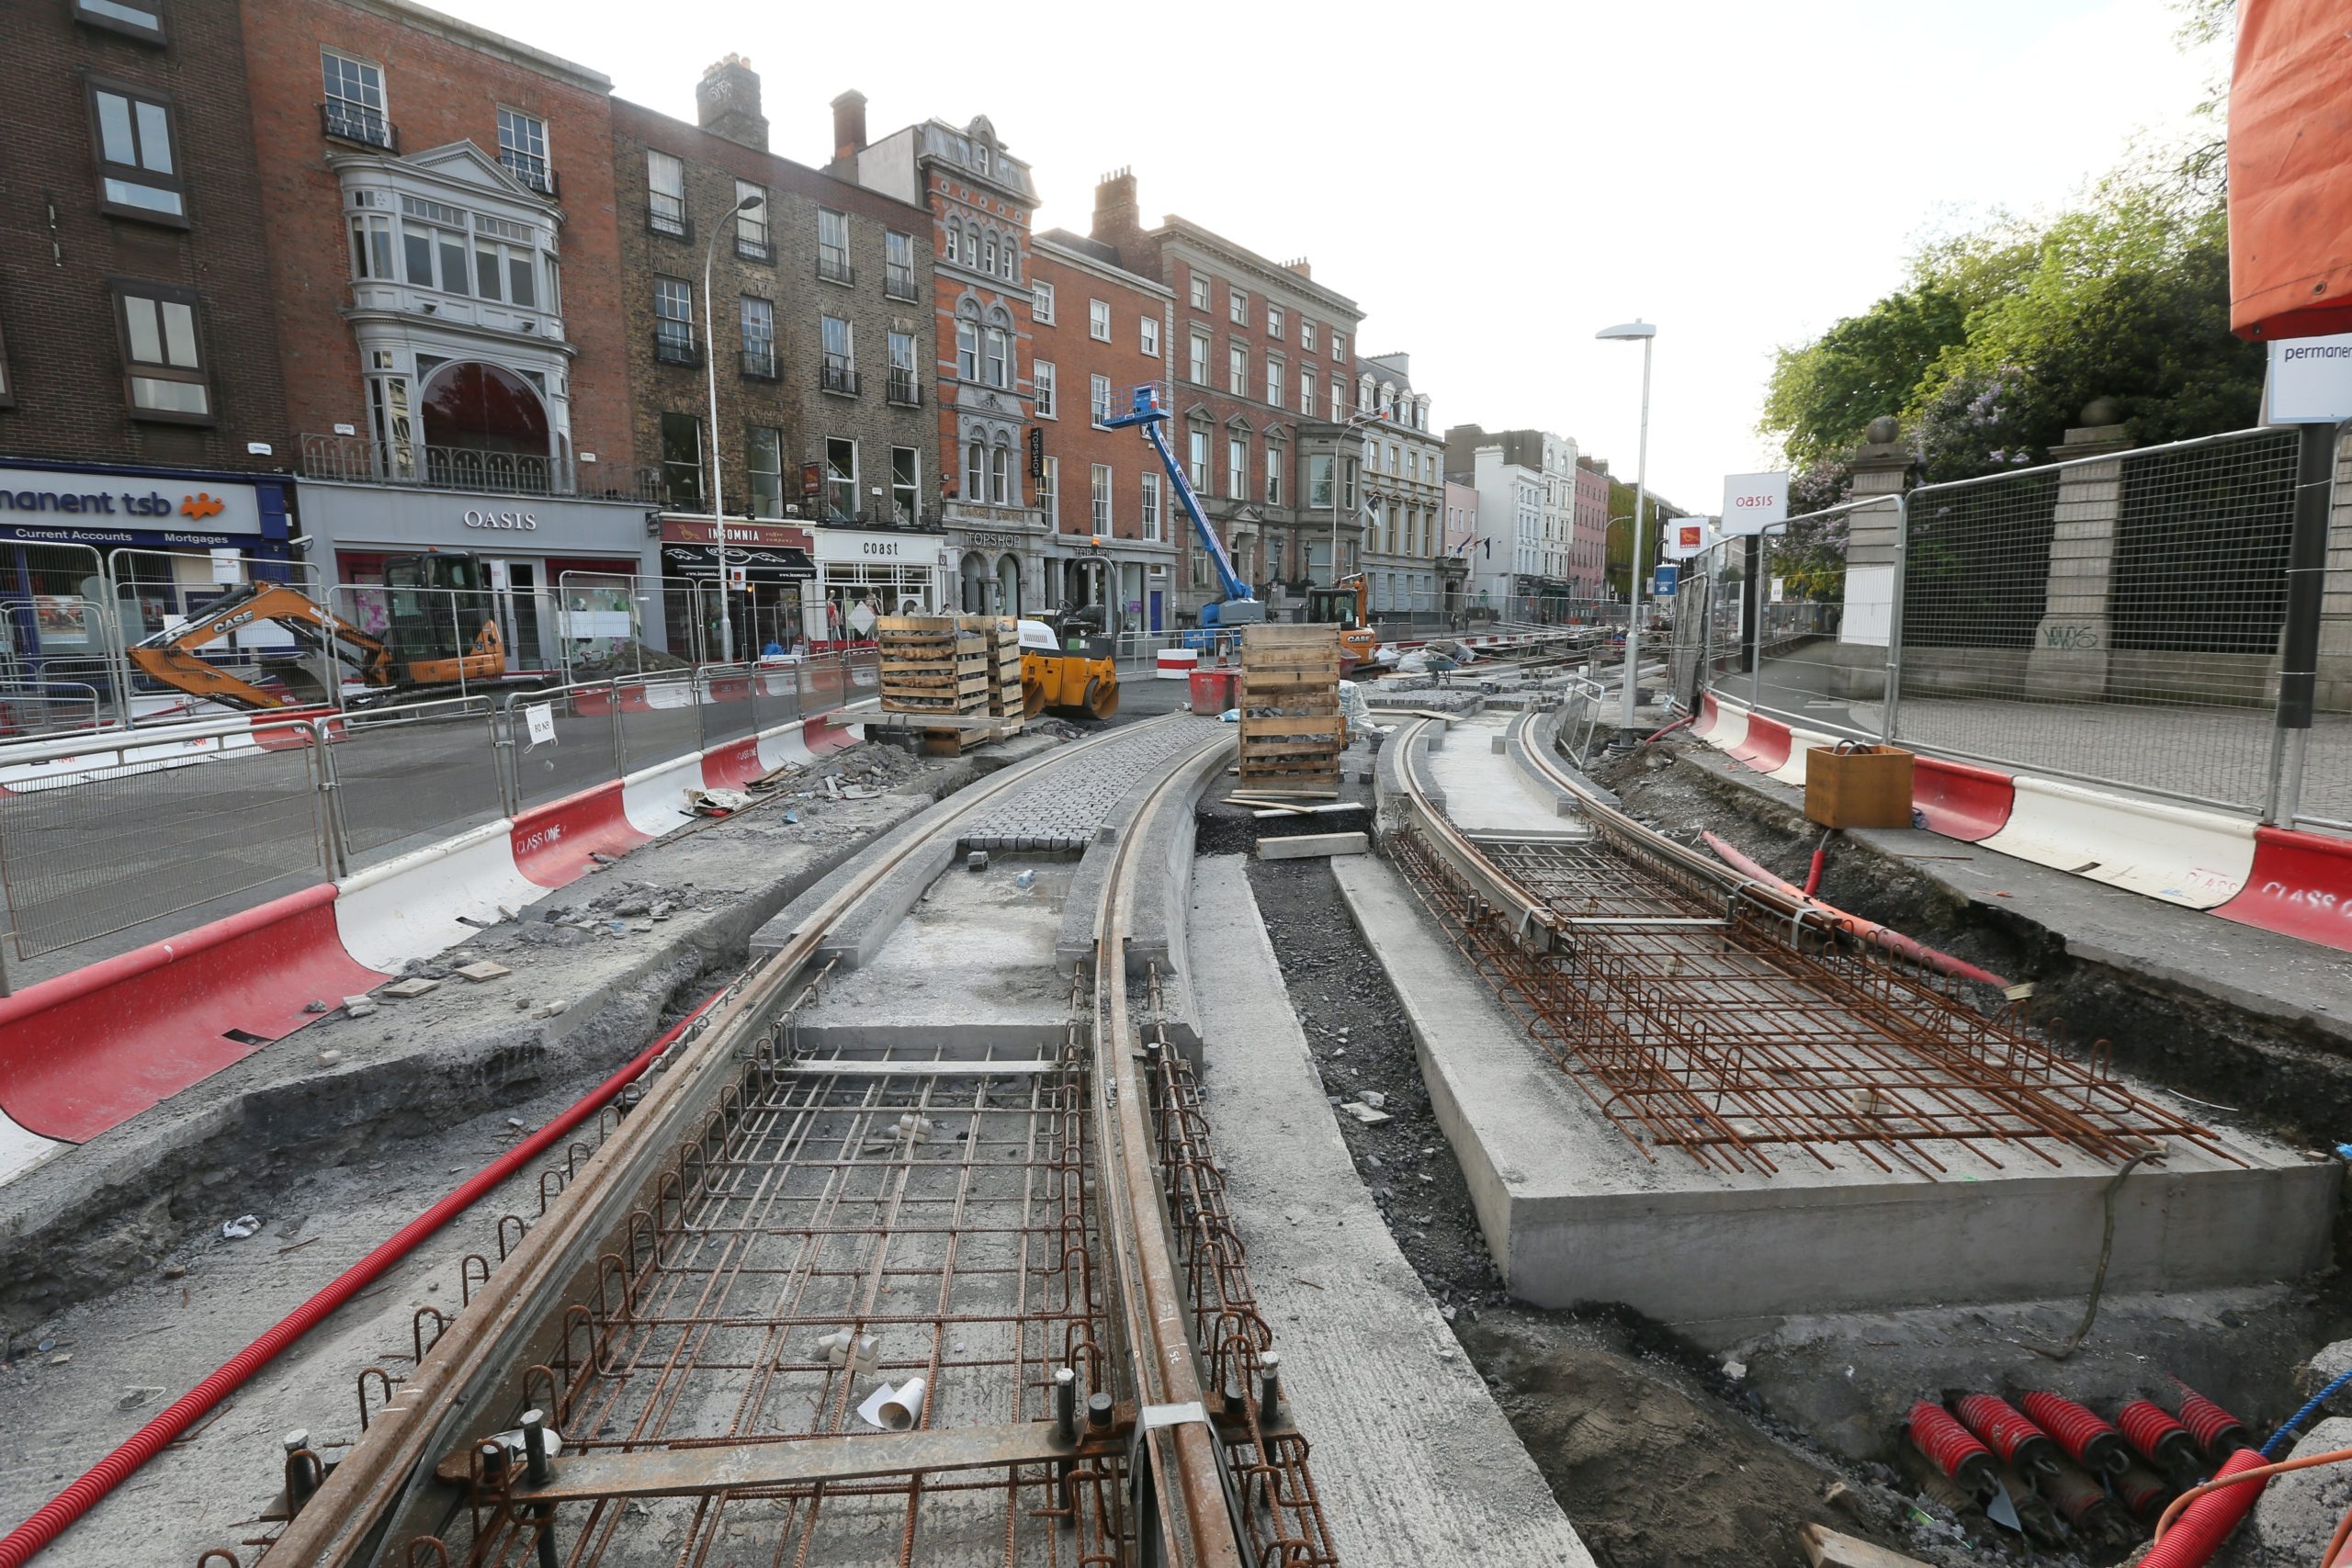
Major infrastructure projects are often judged by what they cost and when they are delivered. Circular 24/2026 shifts the focus towards a different question: whether those investments deliver the benefits they were intended to achieve.
From 1 July 2026, public bodies involved in infrastructure projects are encouraged to take a more structured approach to benefits realisation and communication. The Circular introduces the Benefits Realisation Framework for Infrastructure, which builds on the existing Infrastructure Guidelines by placing greater emphasis on demonstrating that projects deliver their intended benefits throughout the project lifecycle.
What Does Circular 24/2026 Mean in Practice?
In practical terms, the Circular requires public bodies to apply the Benefits Realisation Framework throughout the lifecycle of infrastructure projects and in their public communications about those projects.
This means that:
- Public-facing descriptions of project benefits must be derived from, and remain consistent with, the benefits identified in project appraisal documentation.
- Public bodies should work collaboratively from an early stage of the project to ensure technical, policy and communications teams present a clear and consistent account of:
- a project’s expected benefits; and
- the consequences of delay or non-delivery.
Applying the Benefits Realisation Framework
The Benefits Realisation Framework supports the Infrastructure Guidelines by seeking to ensure that the benefits identified during appraisal are actively managed and assessed across all stages of a project.
In practice, this means public bodies will need to consider:
- The economic, social and environmental benefits expected from a project.
- How those benefits will be measured and monitored.
- Who is responsible for tracking and reporting on benefits.
- How the benefits of investment will be explained clearly to stakeholders and the public.
- The consequences of delay, disruption or non-delivery.
A notable feature of the Framework is the emphasis on the consequences of delay or non-delivery. Public bodies are encouraged to consider not only the benefits of proceeding with a project, but also the economic, social and service impacts that may arise if investment is postponed or abandoned. These impacts could include reduced service capacity, continued infrastructure constraints or missed economic opportunities. The Framework also emphasises accountability by encouraging public bodies to identify who is responsible for ensuring that a project’s expected benefits are realised and reported on.
What Does This Mean for Public Bodies?
The key message of Circular 24/2026 is that infrastructure should not have to speak for itself. Public bodies should be prepared to explain not only the benefits that an investment is expected to deliver, but also the consequences of delay or non-delivery. In doing so, they will need to demonstrate how infrastructure investment supports wider economic, social and environmental outcomes for the communities it is intended to serve.
If you would like to discuss how Circular 24/2026 may affect your organisation, please contact Crowleys DFK’s Risk Consulting team.
 As more public sector bodies invest in new software systems, we are increasingly being asked whether these costs should be capitalised or expensed. The OCAG Technical Bulletin on Intangible Assets and CGAS 31 provide useful guidance in this area. The OCAG bulletin focuses on the accounting treatment of software hosted on the cloud, while CGAS 31 highlights the distinction between research and development costs. Together, they point to two key questions finance teams should consider:
 Ireland’s upcoming Presidency of the Council of the European Union, beginning on 1st July 2026, represents a significant milestone but will also bring a substantial increase in sensitive communications, intergovernmental engagement, and public-facing digital activity. Set against ongoing geopolitical tension, this expanded digital footprint will heighten Ireland’s exposure to hostile cyber activity.